Insurance must be one of the world’s best businesses.
Global data shows consistently high returns on equity, massive scale, and remarkable resilience across cycles.
But it’s not universally great. Only well-run insurers with disciplined underwriting and strong investment management achieve those superior economics.
Here in New Zealand, insurance costs for cars alone have jumped 33% over the past three years. Life insurance premiums have been increasing around 6% per year, well above inflation.
At the same time, there’s also been policy ‘shrinkage’ and tougher terms.
Just a few years ago, my car insurance came with rental-car inclusion as a matter of course. Now it’s an additional benefit you need to pay for.
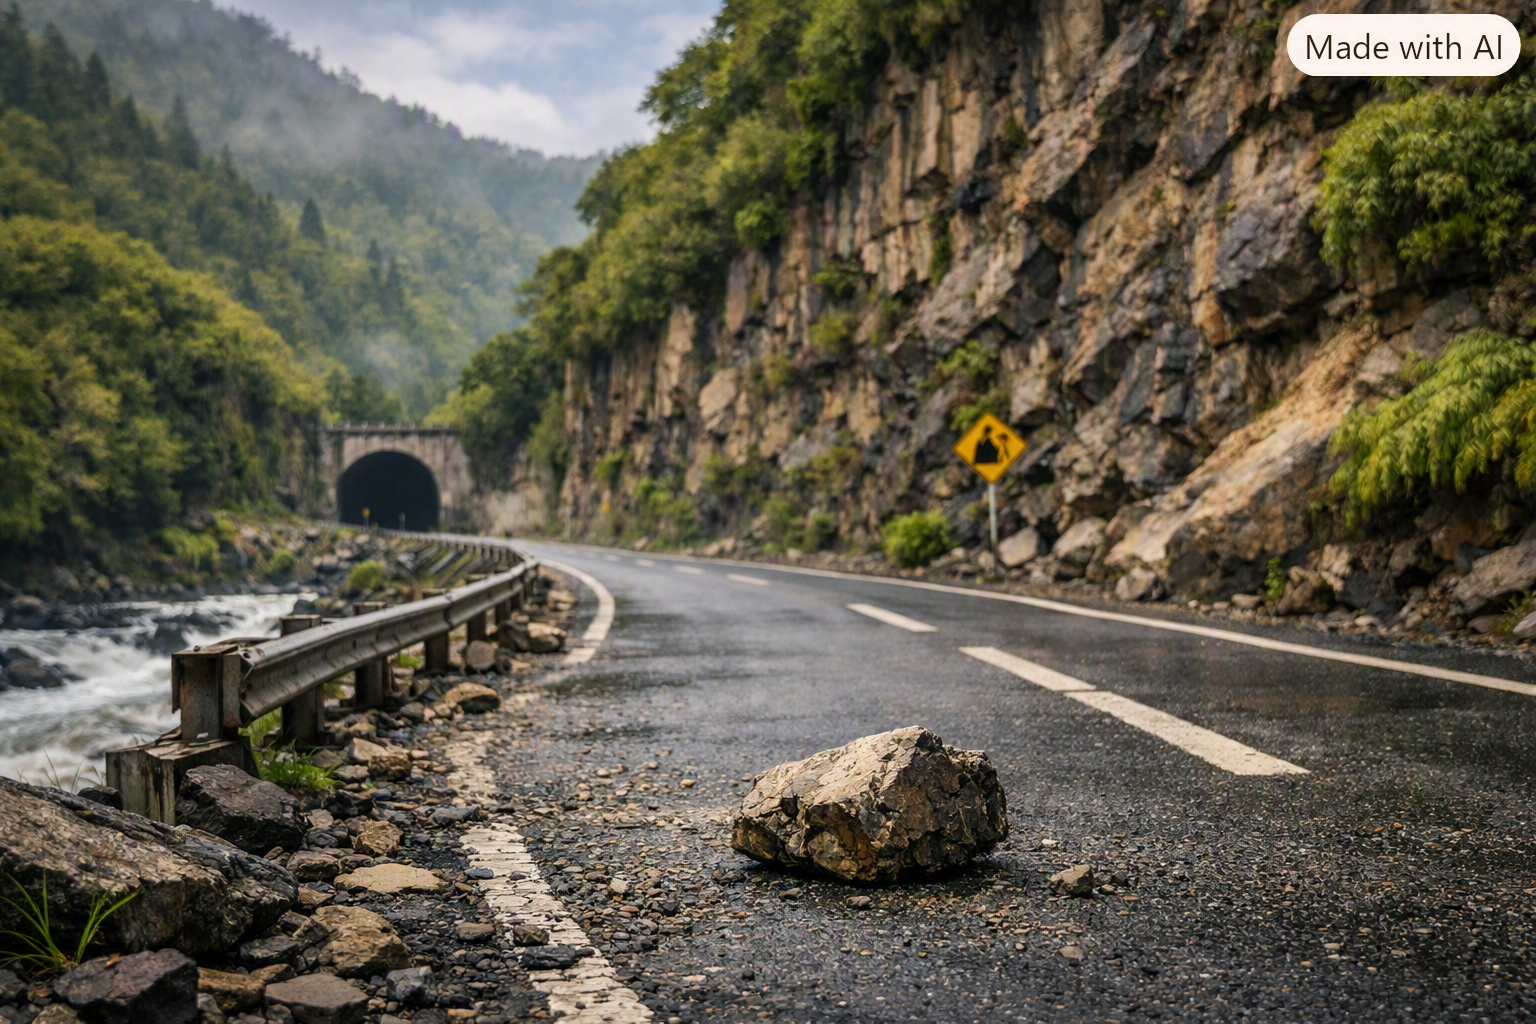
When I hit a rock in the Awakino Gorge and cracked my wheel, the insurance company required the claim to be split into separate events:
1) Hitting the rock and cracking the wheel
2) Damage during salvage of the car
The result? There was no payout due to the excess being invoked in both cases.
Many are carefully considering their risk exposure and reducing cover or excesses after careful determination of the risks. Often, when you have the funds to cover relatively small losses, full insurance for those events is increasingly hard to justify.
Yet there’s one sort of policy that is essential, especially for households dependent on a primary breadwinner with a mortgage.
Demand is increasing, and certain well-capitalised businesses may be ideally positioned.
I am, of course, talking about life insurance. Insurance to cover the biggest bumps on life’s road…
Your first Quantum Wealth Report is waiting for you:
⚡🌎 Start Your Subscription: NZ$37.00 / monthly
⚡🌎 Start Your Subscription: US$24.00 / monthly
Simon is the Chief Executive Officer and Publisher at Wealth Morning. He has been investing in the markets since he was 17. He recently spent a couple of years working in the hedge-fund industry in Europe. Before this, he owned an award-winning professional-services business and online-learning company in Auckland for 20 years. He has completed the Certificate in Discretionary Investment Management from the Personal Finance Society (UK), has written a bestselling book, and manages global share portfolios.