See’s Candies became one of Berkshire Hathaway’s most instructive investments — not because it conquered the world, but because it produced extraordinary returns within a limited niche.
Berkshire acquired See’s in 1972 for $25 million. At the time, the company earned approximately $4 million before tax and required just $8 million of net tangible assets. By 2007, annual pre-tax earnings had reached $82 million, while the capital required to operate the business had increased to only $40 million.
That combination — pricing power, customer loyalty, and minimal reinvestment — made See’s exceptional. The company could increase earnings without retaining most of its cash. By 2014, it had generated approximately $1.9 billion of cumulative pre-tax earnings while requiring only $40 million of additional investment.
However, See’s was not infinitely scalable. Berkshire attempted to reproduce its success in new markets, but those efforts were largely unsuccessful. Its competitive advantage was exceptionally deep within its core niche but difficult to replicate elsewhere.
That did not make See’s a failure. It demonstrated an important distinction between operational scale and economic quality.
A company does not need to become the largest player in its industry to create substantial shareholder value. It must protect its niche, earn attractive returns on capital and avoid reinvesting simply to pursue growth.
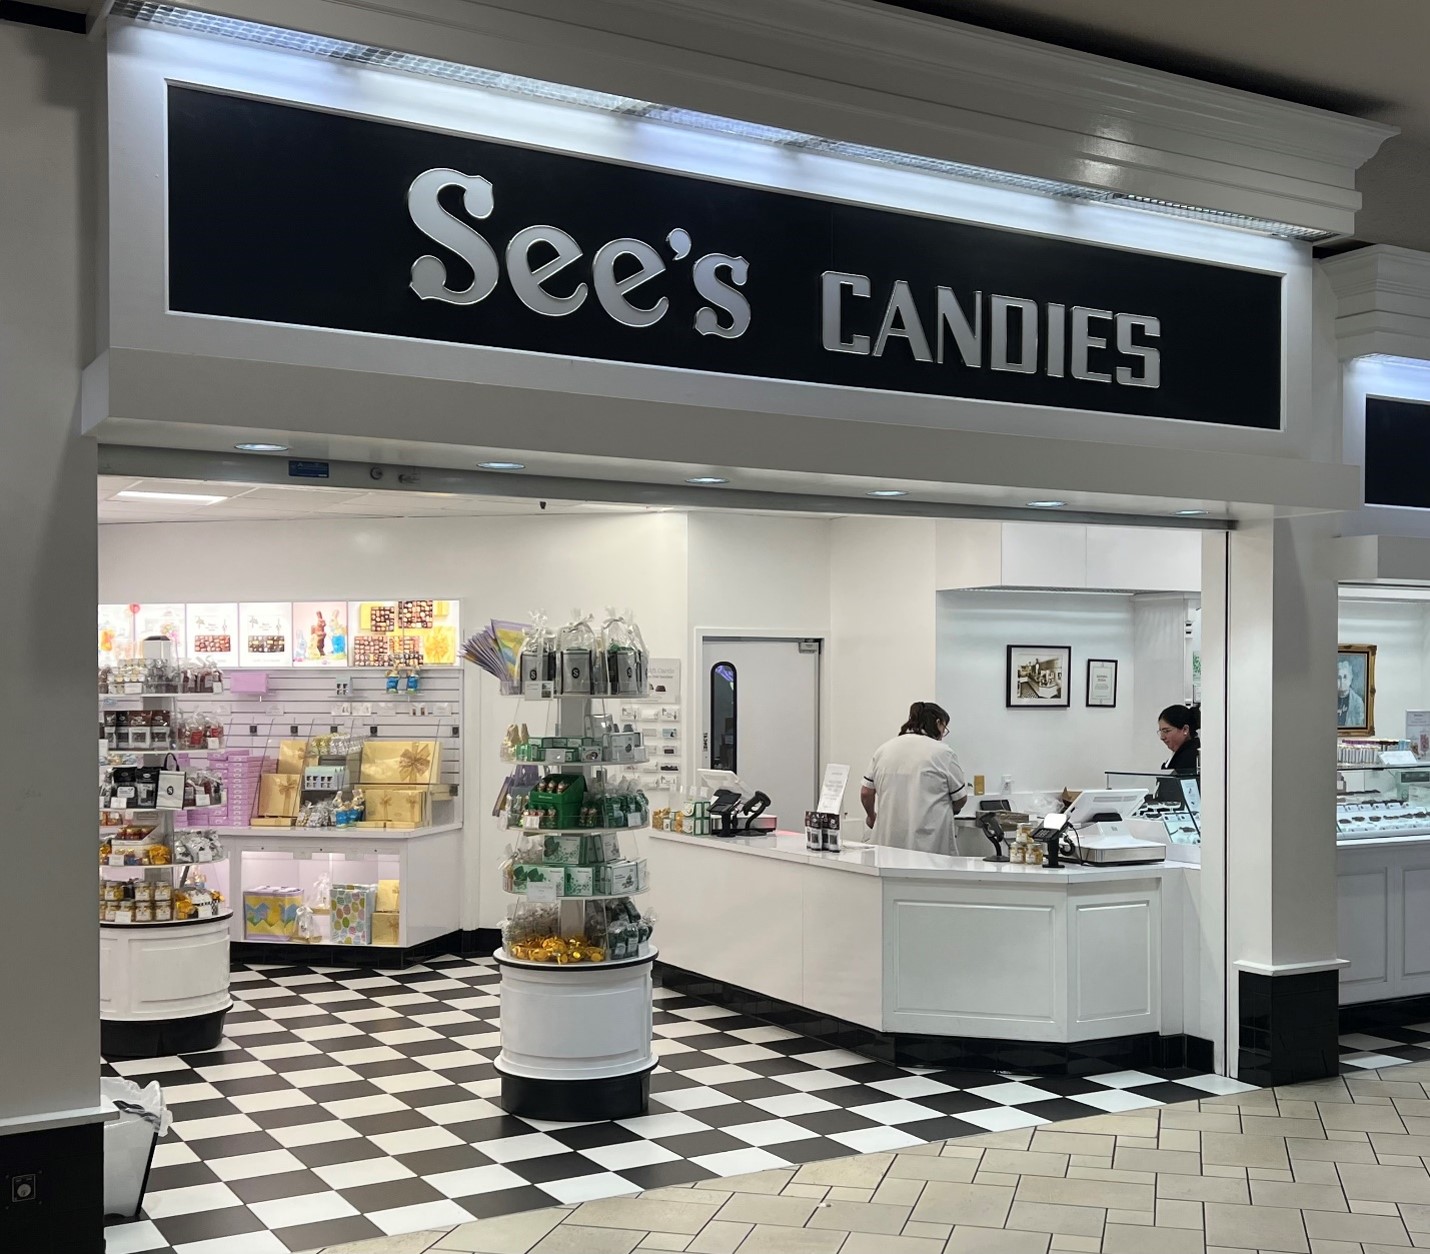
A See’s Candies location in Modesto, California. Source: TaurusEmerald / Wikimedia Commons
But can the same principle apply to a capital-intensive business?
A little-followed NYSE-listed company presents a compelling test. It operates in a specialised segment of a global industry, owns assets that remain essential to major customers, and has secured most of its near-term revenue under long-term contracts. The value of these relationships and the durability of its customer base are not fully reflected in its balance sheet.
Its current earnings, cash flow, and shareholder distributions appear attractive. Yet unlike See’s, this company cannot preserve its earning power with minimal reinvestment.
Its assets physically age. Maintenance costs increase. Efficiency standards change. Eventually, older assets must be sold or replaced. Management has therefore committed substantial capital to a new generation of assets intended to protect the company’s competitive position and future cash flow.
This creates the central investment question: Can management renew the asset base at attractive returns — or is today’s free cash flow partly the liquidation of ageing assets?
If the new assets are supported by profitable contracts and produce returns above the company’s cost of capital, the business may compound despite its capital intensity. If replacement expenditure merely preserves existing revenue while increasing debt and depreciation, apparent value creation could prove temporary.
The lesson from See’s is therefore not that every niche business deserves a premium valuation. It is that capital allocation matters more than expansion alone.
See’s compounded by distributing surplus cash that it did not need. A capital-intensive company must compound differently: by ensuring that every replacement cycle creates more economic value than it consumes.
This analysis identifies the company and examines its niche economics, contracted revenue, dividend sustainability, asset-renewal programme, and expected returns on the next generation of capital…
Your first Quantum Wealth Report is waiting for you:
⚡🌎 Start Your Subscription: NZ$37.00 / monthly
⚡🌎 Start Your Subscription: US$24.00 / monthly
Amit is an analyst and writer at Wealth Morning. He is deeply passionate about understanding how businesses create value, and he brings strong financial modelling skills to his research. Amit has 10+ years of experience across firms like State Street, AMP Capital, and Sydney Water, where he has done analysis on institutional investments ranging from $10 million to $3 billion. He focuses on what matters most: strategic asset allocation and long-term performance. Amit holds a Master of Business Administration in finance from the University of Wollongong. With an intelligent approach to downside protection, he offers a contrarian perspective on global investment strategy.